‘Let me explain’: Corporate disclosures can take a circuitous route
By Tom Fleischman, Cornell Chronicle
The shortest distance between two points is a straight line, but sometimes taking the long way home can have advantages.
In financial disclosures, particularly by companies that are coming out of tough times, a firm’s verbal circuitousness – sharing of information contextualized in multiple ways – can paint a fuller picture of a company’s prospects, a Cornell research group found.
“CEOs shouldn’t necessarily try to be as brief as possible,” said Nicholas Guest, assistant professor of accounting in the Samuel Curtis Johnson Graduate School of Management, in the Cornell SC Johnson College of Business.
“Talking about topics such as revenues in multiple contexts – their financing efforts, their relationships with customers and their attempts to satisfy regulators – might actually be useful,” he said, “if there is an investor who has the time and energy and sophistication to sit down and process it all.”
Guest is a co-author of “Circuitousness in Disclosure Narratives,” which was published Aug. 17 in The Accounting Review. Guest’s co-author is Jiawen Yan, Ph.D. ’25, now an assistant professor of accounting at the National University of Singapore.
The idea of verbal circuitousness has been around for decades and was first associated with a method of teaching in academics, in what’s known as the “spiral curriculum.”
“The idea is that a teacher should start simple, introduce a concept, and then come back to it at different times, contextualized maybe at a higher difficulty level as they go,” Guest said. “Once the foundational elements are there for the student, they start to get the picture. And if you’re a CEO, explaining your financial situation in this way, your investors get the picture.”
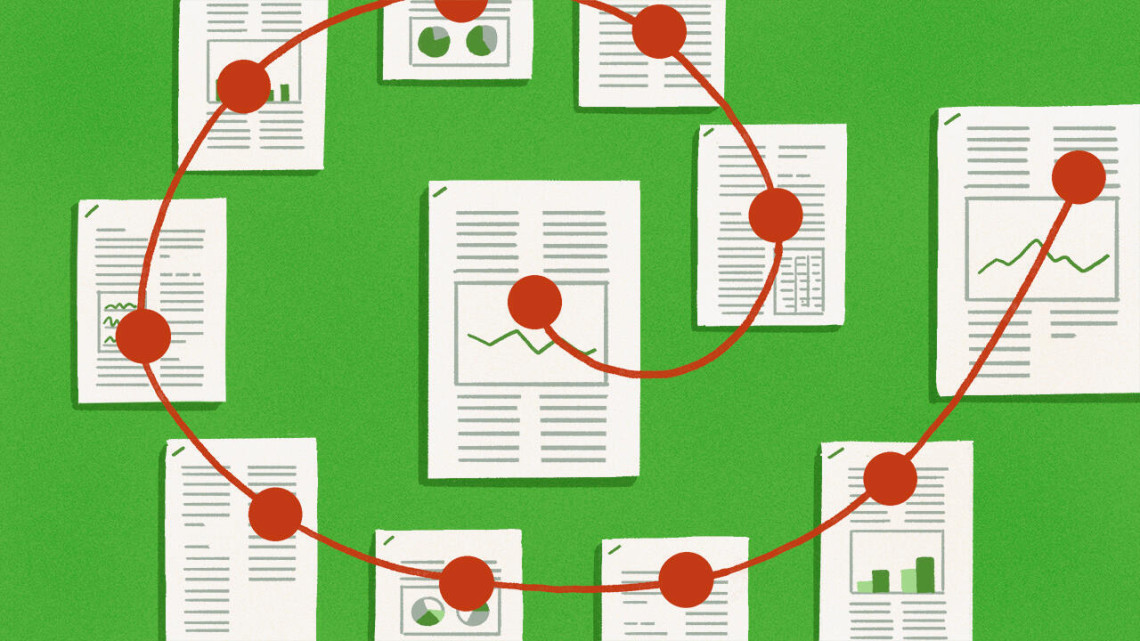
In this context, verbal circuitousness is defined as the ratio of the length of the path a text actually took to the length of the shortest path a text could have taken to cover all points.
One of the researchers’ hypotheses was that circuitousness is more prevalent when a firm is struggling but on the verge of recovery, as it will present a lot of information for analysts and other market watchers to process. The cost of that processing comes in different forms, such as cognitive effort or computational resources used to gather and digest the information, Guest said.
To find out if their hypotheses were true, the researchers employed natural language processing and machine learning to analyze more than 13,000 management discussion and analysis (MD&A) filings, extracted from annual reports firms submitted to the Securities and Exchange Commission (SEC) from 1997 through 2019. They split and tokenized each MD&A into chunks of approximately 250 words for computer-modeling purposes, following a method devised five years ago in marketing research by Olivier Toubia of Columbia University, and Jonah Berger and Johoshua Eliashberg of the University of Pennsylvania.
Guest and Yan zeroed in on firms with negative earnings, which they hypothesized would benefit most from circuitousness. The team compared those firms’ circuitousness to three commonly used indices: the Fog index, which captures linguistic complexity; document length; and repetition.
Guest noted that circuitousness is not the same thing as obfuscation – making a message hard to understand – although there are reasons a CEO might want to do that, and not just when they have bad news.
“If they release all the good news right away,” he said, “they might attract the attention of competitors, who might say, ‘Hey, why don’t we copy what they’re doing?’ Or policymakers who might say, ‘Hey, we should be taxing them more.’”
Circuitousness can be visualized by plotting each chunk of text as a point on a vector; each point’s position is determined by the average of the word vectors. The distance between points represents similarities (shorter distance) and differences (longer) in the semantic relationship between chunks. Guest and Yan examined the path between points, keeping them in order to capture progression from earlier to later chunks and to measure the spread of related information throughout the narrative – i.e., circuitousness.
The researchers found a positive correlation between circuitousness and firms that eventually experienced earnings upturns; the correlation wasn’t there for firms with impending downturns. They also found that higher MD&A circuitousness is associated with more EDGAR (Electronic Data Gathering, Analysis and Retrieval) downloads from the SEC, which investors use to process information.
Guest said this research could be useful for most market watchers and participants.
“Investors could use our circuitousness measure as a quick screen to identify companies that are about to have a turnaround, which is a really important part of value investing,” he said. “And identifying circuitousness could also be useful for analysts and journalists trying to identify topics managers are struggling to explain.”
This work was supported in part by a Dyckman Research Grant awarded to Yan for his doctoral proposal, which spurred this research.
Media Contact
Adam Allington
Get Cornell news delivered right to your inbox.
Subscribe